Understanding financial adviser fees for business owners in Sydney is crucial for making informed decisions about your financial future. While costs can vary significantly, most advisers operate on transparent fee structures, moving away from commission-based models towards fee-for-service arrangements. This shift ensures that the advice you receive is directly aligned with your financial goals, rather than product sales.
This comprehensive guide will explore the various fee models employed by financial advisers in Sydney, provide illustrative pricing benchmarks for different business owner profiles, and clarify the tax implications of these fees. We’ll also cover essential questions to ask about fees and how to interpret key documents like the Fee Disclosure Statement and Statement of Advice, helping you navigate the cost of financial planning for your business.
Financial adviser fees for business owners: fee models at a glance
For business owners in Sydney seeking financial advice, understanding the different fee models is the first step towards evaluating value. The Australian financial services landscape has largely transitioned to fee-for-service models, promoting greater transparency and reducing potential conflicts of interest. The Australian Securities and Investments Commission (ASIC) provides guidance on these structures, emphasising clarity for consumers, particularly regarding financial adviser fees for business owners in Sydney.
Common fee structures include fixed fees, hourly rates, and percentage-based fees. A fixed fee is a set amount charged for a specific service, such as developing a Statement of Advice (SOA) or creating a business succession plan. Hourly rates are self-explanatory, where you pay for the time the adviser spends on your case. Percentage-based fees, often applied to assets under management (AUM), mean the adviser charges a percentage of the value of your investment portfolio. Each model has its advantages and disadvantages, depending on the complexity of your financial situation and the scope of advice required. For comprehensive financial planning for business owners in Australia, understanding these models is key to finding transparent financial advice fees.
Common fee structures for financial advice
- Fixed Fees: A predetermined amount for a defined scope of work. This is common for initial advice, specific projects like superannuation advice, or creating a financial plan. It offers cost certainty and is often preferred by small business financial advisers for discrete tasks.
- Hourly Rates: Charges based on the time spent by the adviser. This can be suitable for ad-hoc advice or when the scope of work is less defined initially. Rates can vary significantly based on the adviser’s experience, specialisation, and the complexity of the business owner financial advice required.
- Percentage-Based Fees: Typically a percentage of the assets managed by the adviser. This model is often used for ongoing investment management and can align the adviser’s interests with the growth of your portfolio. It’s a common structure for those seeking long-term investment management.
- Hybrid Models: A combination of the above, for instance, a fixed fee for initial advice followed by a percentage-based fee for ongoing investment management. This offers flexibility, allowing for a tailored approach to Sydney financial planning costs.
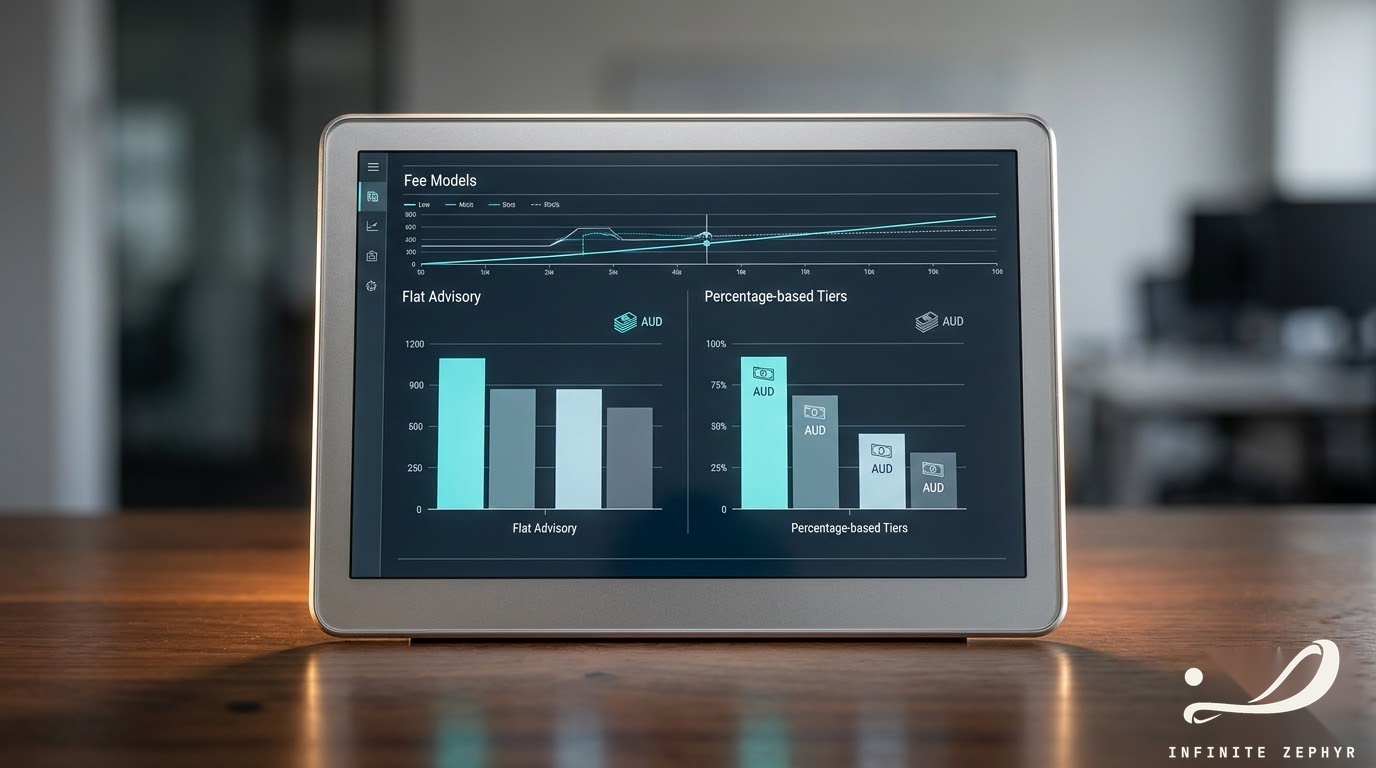
Fixed fee, flat plus overlay, percentage of assets, or hybrid: which fits a business owner?
Choosing the right fee structure depends heavily on the specific needs and financial complexity of a business owner. Each model offers distinct advantages and may be more suitable for different stages of a business’s lifecycle or types of advice required. For instance, a small business owner seeking initial advice on setting up an SMSF might prefer a fixed fee for clarity, while a more established enterprise with significant investment portfolios might find a percentage-based fee for ongoing management more appropriate, especially when considering adviser fee structures in Australia.
A ‘flat plus overlay’ model might involve a fixed fee for core financial planning services, with an additional percentage or fixed amount for specific, more complex services like business succession planning or intricate tax strategies. This allows for a tailored approach that addresses both general financial planning needs and specialised business requirements. When considering financial advisory services like these, it’s important to discuss the fee structure in detail with your adviser to ensure it aligns with your expectations and budget. Understanding these nuances is key to managing your financial adviser fees for business owners in Sydney.
| Fee Model | Best Suited For Business Owners Who… | Potential Advantages | Potential Disadvantages |
|---|---|---|---|
| Fixed Fee | Need specific, one-off advice (e.g., initial financial plan, business succession planning, SMSF setup). | Cost certainty, clear scope of work, ideal for defined projects. | May not cover ongoing advice, less flexible for evolving needs, potentially higher upfront cost for comprehensive plans. |
| Hourly Rate | Require ad-hoc advice, have complex but undefined needs, or prefer to pay only for time spent. | Flexibility, only pay for actual work done, suitable for consultations or specific queries. | Cost can be unpredictable if scope expands, requires careful tracking, may not be cost-effective for extensive, ongoing advice. |
| Percentage of Assets (AUM) | Have significant investment portfolios requiring ongoing management and monitoring. | Adviser’s interests align with portfolio growth, comprehensive ongoing service, often includes regular reviews. | Fees increase with asset value, may be higher for large portfolios regardless of activity, can be perceived as less transparent on a dollar basis. |
| Hybrid Model | Need a combination of initial project-based advice and ongoing investment management. | Combines certainty for initial work with ongoing support, highly customisable to individual business owner financial advice needs. | Can be more complex to understand initially, requires clear communication on what each component covers. |
Illustrative pricing by business owner profile
The cost of financial advice for business owners in Sydney can vary widely, influenced by factors such as the complexity of their financial situation, the scope of services required, and the adviser’s experience and specialisation. While specific figures are not provided here, general market benchmarks suggest that initial advice, such as developing a comprehensive financial plan, might range from a few thousand dollars for simpler situations to significantly more for complex business structures involving multiple entities, extensive investment portfolios, or intricate estate planning. These figures are general observations for financial adviser fees for business owners in Sydney.
Ongoing advice fees, particularly those based on a percentage of assets under management, typically fall within a range of 0.5% to 1.5% per annum of the managed assets. For business owners with Self-Managed Super Funds (SMSFs), additional fees for SMSF advice fees in Sydney and administration can apply, reflecting the specialised knowledge and compliance requirements involved. It’s important to remember that these are general market observations, and actual costs will depend on the individual adviser and the specific services agreed upon. For detailed information on Infinite Zephyr‘s approach to financial planning, it’s best to consult directly. You can also review their pricing philosophy for more insights.
Factors influencing financial adviser fees
- Complexity of Financial Situation: Businesses with multiple entities, complex tax structures, diverse investments, or intricate succession planning needs will generally incur higher fees due to the increased time and expertise required.
- Scope of Services: A comprehensive financial plan covering personal and business finances, superannuation advice, investments, and risk management will cost more than advice on a single issue. The breadth of services directly impacts the overall cost of financial planning.
- Adviser Experience and Specialisation: Highly experienced advisers or those specialising in specific areas like business finance or SMSFs may charge higher rates, reflecting their advanced knowledge and track record.
- Ongoing vs. One-off Advice: Ongoing advice typically involves a different fee structure (e.g., percentage-based) compared to one-off project fees, offering continuous support and regular reviews.
- Geographic Location: While less pronounced in the digital age due to video consultations, advisers in major metropolitan areas like Sydney may have slightly different fee structures compared to regional areas, though competition often balances this.
- Compliance Costs: The regulatory environment in Australia, overseen by ASIC, requires significant compliance efforts from financial advisers, which can be factored into their fees.
Are financial adviser fees tax-deductible for a business owner?
Tax laws are complex and subject to change. This information is a general summary only and should not be relied upon as formal tax advice. For business owners in Australia, the tax deductibility of financial adviser fees is an important consideration that can impact the net cost of advice. Generally, fees paid for financial advice that relates to managing your tax affairs, investments, or income-producing activities may be deductible. However, the specific rules can be nuanced and depend on the nature of the advice received, making it a key aspect of business owner financial advice.
According to the Australian Taxation Office (ATO), fees paid for advice on managing your income-producing investments are typically deductible. This can include advice related to your business investments, superannuation, or other assets held to generate income. However, advice that is capital in nature, such as advice on setting up a new business structure or purchasing a new investment property, may not be immediately deductible but could form part of the cost base of the asset. It is always advisable to consult with a tax professional or refer to the ATO’s specific guidance on financial advice fees to understand your specific situation and how it impacts your financial adviser fees for business owners in Sydney.
Key considerations for tax deductibility
- Income-Producing Activities: Fees related to advice on investments or activities that generate assessable income are generally deductible. This includes advice on managing existing business assets or investment portfolios.
- Capital vs. Revenue: Advice that is capital in nature (e.g., establishing a new business, acquiring a significant asset) is typically not deductible in the year it’s incurred, unlike advice related to ongoing income generation (revenue).
- Superannuation Advice: Fees for advice on superannuation, including SMSFs, can be deductible under certain conditions, particularly if the advice relates to the ongoing management of your super fund and its income-producing assets.
- Personal vs. Business Advice: It’s crucial to distinguish between advice for your personal finances and advice directly related to your business operations, as deductibility rules may differ. Proper record-keeping is essential for substantiating claims.
- Compliance Costs: Certain compliance costs associated with managing investments or business structures may also be deductible, further reducing the net cost of financial planning.
Reading your Fee Disclosure Statement and Statement of Advice
When engaging a financial adviser, two critical documents you will receive are the Fee Disclosure Statement (FDS) and the Statement of Advice (SOA). These documents are mandated by ASIC to ensure transparency and provide you with a clear understanding of the services you will receive and the associated costs. Understanding how to read and interpret these documents is essential for any business owner seeking financial advice in Sydney, ensuring you comprehend the full scope of financial adviser fees for business owners in Sydney.
The FDS provides a summary of the fees paid, the services received, and the services you were entitled to receive over the previous 12 months. It also outlines the services you will be entitled to receive in the next 12 months and the estimated fees for those services. The SOA, on the other hand, is a comprehensive document that outlines the personal financial advice provided to you, including your financial situation, objectives, and needs, the recommended strategies, and the reasons for those recommendations. It also details all fees and charges associated with the advice and any products recommended. Always review these documents carefully and ask your adviser to clarify anything you don’t understand, especially concerning transparent financial advice fees.
What to look for in your FDS and SOA
- Clear Fee Breakdown: Ensure all fees are clearly itemised, including initial fees, ongoing fees, and any third-party costs. Look for a detailed explanation of how each fee component is calculated.
- Service Scope: Verify that the services outlined in the FDS and SOA match your understanding and expectations. This includes specific deliverables, review schedules, and communication protocols.
- Disclosure of Conflicts: The SOA should disclose any potential conflicts of interest the adviser may have, providing you with full transparency about their recommendations.
- Reasonableness of Advice: The SOA should clearly explain why the recommended strategies are suitable for your specific situation, linking them back to your stated financial objectives and needs.
- Review Dates: Note any review dates for ongoing advice services mentioned in the FDS, as these indicate when your plan will be re-evaluated and adjusted.
- Product Recommendations: Understand the rationale behind any recommended financial products and how they align with your overall financial strategy.
Questions to ask about fees
Engaging a financial adviser is a significant decision for any business owner. To ensure you receive value for money and understand the full scope of costs, it’s vital to ask the right questions about fees upfront. Transparency in financial advice fees is paramount, and a reputable adviser will be open and clear about their charges. This proactive approach helps you compare different advisers and make an informed choice regarding Sydney financial planning costs.
When discussing fees, don’t hesitate to ask for a detailed breakdown of all potential costs, including any ongoing charges or fees for specific services like SMSF advice fees in Sydney. Understanding the total cost of financial planning, not just the initial consultation, is crucial. The Financial advice costs – Moneysmart.gov.au resource provides further guidance on what to consider. Remember, the goal is to find a small business financial adviser whose fee structure aligns with your needs and provides transparent financial advice fees, ensuring you get the best value for your financial adviser fees for business owners in Sydney.
Essential questions to clarify fee structures
- What is your typical fee structure for business owners, and how does it apply to my specific situation and business owner financial advice needs?
- Can you provide a detailed breakdown of all potential fees, including initial, ongoing, and any third-party costs, such as platform fees or product charges?
- What services are included in your fees, and what might incur additional charges? Is there a clear scope of work for each fee component?
- How often are fees reviewed or adjusted, and how will I be notified of any changes to my adviser fee structures in Australia?
- Do you receive any commissions or other benefits from product providers, and how are these disclosed to clients?
- What is the total estimated cost for the advice I am seeking over the next 12 months, including all potential charges?
- How do your fees compare to other financial advisers in Sydney offering similar services and levels of expertise?
- What is your process for billing, and what payment options are available for financial adviser fees for business owners in Sydney?
Frequently Asked Questions about Financial Adviser Fees for Business Owners in Sydney
What is a typical fee structure for a financial adviser in Sydney working with business owners?
Typical fee structures for financial advisers in Sydney working with business owners often include fixed fees for specific projects (e.g., initial financial plan, business succession planning), hourly rates for ad-hoc advice, or percentage-based fees for ongoing investment management. Hybrid models combining these approaches are also common, tailored to the complexity of the business owner’s financial situation and the scope of business owner financial advice required.
Are financial adviser fees tax deductible for Australian businesses?
Financial adviser fees can be tax deductible for Australian businesses if the advice relates to managing income-producing investments or tax affairs. However, advice that is capital in nature (e.g., setting up a new business) may not be immediately deductible. It’s crucial to consult with a tax professional or the ATO for specific guidance on your situation, as tax laws are complex and subject to change.
How do I compare financial adviser fees in Sydney?
To compare financial adviser fees in Sydney, request a detailed breakdown of all costs, including initial and ongoing fees, and understand what services are included. Compare fee structures (fixed, hourly, percentage) against the scope of advice you need. Also, consider the adviser’s experience, specialisation, qualifications (e.g., checking the ASIC Financial Advisers Register), and client testimonials, not just the price.
What services are usually included in a financial adviser’s fee for business owners?
Services usually included in a financial adviser’s fee for business owners can encompass comprehensive financial planning, investment strategy, superannuation advice (including SMSFs), risk management, business succession planning, and retirement planning. The exact scope will be detailed in your Statement of Advice (SOA) and Fee Disclosure Statement (FDS), ensuring transparent financial advice fees.
Is it better to pay a fixed fee or a percentage-based fee for financial advice?
The ‘better’ option between a fixed fee and a percentage-based fee depends on your needs. A fixed fee offers cost certainty for specific projects or initial advice. A percentage-based fee, often for assets under management, aligns the adviser’s interests with portfolio growth and typically covers ongoing investment management. Your choice should reflect the nature and duration of the advice required, and the overall cost of financial planning.
What questions should I ask a financial adviser about their fees before engaging them?
Before engaging a financial adviser, ask for a clear breakdown of all fees (initial, ongoing, third-party), what services are included, how often fees are reviewed, and if they receive any commissions. Also, inquire about their typical fee structure for business owners and how it applies to your specific financial situation, ensuring you understand all financial adviser fees for business owners in Sydney.
Do financial advisers in Sydney charge differently for small businesses versus larger enterprises?
Yes, financial advisers in Sydney may charge differently for small businesses versus larger enterprises. Fees often reflect the complexity of the financial situation, the volume of assets, and the scope of services required. Larger enterprises with more intricate structures, diverse investments, or extensive succession planning needs typically incur higher fees due to the increased time and specialisation involved, impacting the overall Sydney financial planning costs.
Tax, superannuation, and regulatory information in this article is based on legislation and ATO/ASIC guidance current as of 2026. These rules are complex and subject to change, and this article is not updated retrospectively when they do. This information is a general summary only and should not be relied upon as formal tax advice — always confirm current rules with a registered tax agent or the ATO directly.
General Advice Warning: This information is general in nature only and does not constitute personal financial, legal, or tax advice. It has been prepared without taking into account your individual objectives, financial situation, or needs. Before acting on any information, you should consider its appropriateness having regard to your objectives, financial situation, and needs, and seek professional advice from a licensed financial adviser and registered tax agent. Past performance is not a reliable indicator of future performance.
This information is provided by Infinite Zephyr & Wealth Pty Ltd (ABN 12 628 624 279), an Authorised Representative (AR 001268024) of NDT Capital Pty Ltd (AFSL 558899). You can verify this authorisation on the ASIC Financial Advisers Register. For dispute resolution, contact the Australian Financial Complaints Authority (AFCA).